0

Co-Lending: One Loan, Two Lenders — and a Very Different Lending Lifecycle

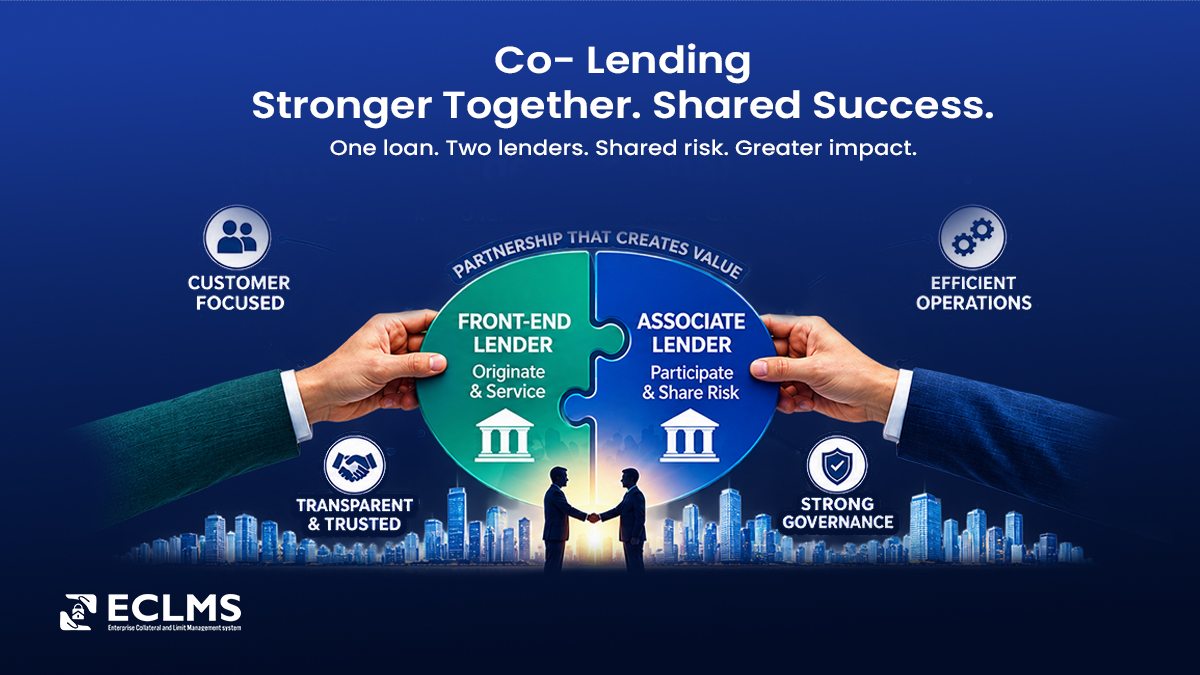
Co-lending is gradually becoming an important part of the lending landscape, particularly as banks and other regulated lenders look to combine their respective strengths in customer reach, origination, funding and risk participation.

At first glance, the concept appears simple.

Two lenders agree to finance a borrower. The loan is shared between them in an agreed proportion. Interest and other economic benefits are shared, and so is the credit risk.

But from a banker’s perspective, co-lending is much more than simply dividing a loan between two lenders.

The moment two lending institutions participate in the same credit exposure, the traditional lending lifecycle changes significantly.

A conventional loan largely follows a linear relationship:

Bank → Borrower → Disbursement → Repayment → Closure

A co-lending relationship is different.

There is still one borrower and one underlying credit requirement, but behind the loan there are two participating lenders, separate financial exposures, agreed responsibilities, shared cash flows and a continuing requirement to keep both lenders aligned throughout the life of the facility.

Understanding this lifecycle is important for bankers who will increasingly deal with such portfolios.

Article content

It Starts Before the Borrower Arrives

In conventional lending, the relationship effectively starts when the borrower approaches the bank.

In co-lending, an important relationship already exists before that happens — the relationship between the participating lenders.

The lenders first need to agree on the broad framework within which loans will be originated and shared.

They need to decide what type of borrowers and products will be covered, which lender will originate the loans, how the credit exposure will be shared, who will interact with customers, who will service the loans and how collections, income, defaults and recoveries will be dealt with.

This arrangement becomes the foundation for every loan subsequently originated under the program.

This is the first important distinction:

A co-lending loan operates within two relationships — the lender-to-lender relationship and the lender-to-borrower relationship.

Both must remain aligned throughout the loan lifecycle.

Who Faces the Customer?

Normally, one lender takes the lead in originating the customer relationship.

It may source the borrower, collect the application, undertake KYC and due diligence, evaluate the proposal, arrange documentation and remain the principal point of contact for the borrower.

The partner lender may not have the same level of day-to-day interaction with the customer, but it nevertheless has a real financial exposure to the borrower.

This creates an interesting operating model.

From the customer’s perspective, the experience should remain reasonably seamless.

Behind the scenes, however, both lenders need sufficient information to understand and monitor their respective exposure.

The customer-facing lender therefore does more than originate a loan. It becomes an important information and servicing bridge between the borrower and the participating lender.

Credit Assessment Remains Important to Both Lenders

The originating lender may undertake the detailed credit assessment, but participation in a loan cannot simply be treated as the purchase of a percentage of an unidentified pool.

The partner lender needs to know what it is participating in.

Depending upon the agreed arrangement, the partner may rely upon predefined eligibility and underwriting parameters or undertake additional assessment before taking its share.

This creates two related but distinct decisions:

Should this borrower be given the loan?

and

Should the partner lender participate in this particular exposure?

For bankers, this distinction becomes important because origination and participation are not necessarily the same credit decision.

One Loan — But Two Financial Exposures

Suppose a borrower receives a loan of ₹1 crore.

Under the agreed co-lending arrangement:

Lender A participates for 20% — ₹20 lakh

Lender B participates for 80% — ₹80 lakh

The borrower sees a ₹1 crore loan.

But each lender sees only its respective financial exposure.

This distinction must remain intact throughout the life of the loan.

If the borrower subsequently repays ₹10 lakh of principal, the overall outstanding may become ₹90 lakh, but the corresponding lender-level positions must also change.

The same principle applies to interest, overdue amounts, prepayments, write-offs and recoveries.

Co-lending therefore requires bankers to think about a loan simultaneously at two levels:

What does the borrower owe?

and

What is each lender’s economic interest in that amount?

Disbursement Is No Longer a Single-Lender Event

In conventional lending, the bank sanctions the facility and disburses the amount.

Under co-lending, funding itself becomes a coordinated activity.

Each lender has to contribute its agreed share, and the borrower ultimately needs to receive the intended disbursement.

Consider a ₹1 crore disbursement under an 80:20 arrangement.

One lender must ultimately fund ₹80 lakh and the other ₹20 lakh.

If one lender’s contribution is delayed, short-funded or incorrectly accounted for, the issue is no longer merely an internal reconciliation problem. It can potentially affect the borrower experience and the financial positions of both lenders.

The lenders therefore need visibility over:

What was supposed to be funded? What was actually funded? When was it funded? What was disbursed to the borrower?

Pricing Introduces Another Dimension

Pricing under co-lending can also be different from conventional lending.

The participating lenders may have different expected returns on their respective portions of the exposure. At the same time, the borrower needs clarity regarding the effective interest rate applicable to the loan.

This introduces the concept of a blended interest rate.

If 20% of a loan carries one lender’s economic rate and the remaining 80% carries another, the overall borrower pricing needs to appropriately reflect the agreed structure.

There is another commercial aspect that should not be confused with interest.

The customer-facing lender may perform sourcing, documentation, servicing, collection and other operational activities on behalf of the arrangement. Compensation for such activities may therefore form part of the commercial understanding between the lenders.

From a banker’s perspective, it is useful to distinguish:

return for assuming credit exposure

from

compensation for performing services.

The Real Operational Challenge Begins After Disbursement

Sanction and disbursement receive considerable attention in lending projects.

In my view, however, the more interesting challenge in co-lending begins after the money has been disbursed.

The borrower starts paying instalments.

Suppose an EMI of ₹1 lakh is received.

That ₹1 lakh is not simply an amount to be divided 80:20.

It may contain principal, normal interest, overdue interest, charges or other amounts.

Each component first needs to be appropriately recognised against the borrower’s obligation.

Only thereafter can the economic entitlement of the participating lenders be determined.

This creates an important distinction:

Collection from the borrower is one event. Distribution of that collection between lenders is another.

The two should not be confused.

Collection Distribution Becomes the Heart of the Operating Model

Consider a borrower payment of ₹1 lakh comprising:

Principal — ₹60,000 Interest — ₹38,000 Other charges — ₹2,000

Principal may broadly follow the lenders’ participation ratio.

Interest distribution may reflect their respective economic entitlement.

Some charges may belong to the servicing lender, while others may need to be treated differently under the agreement.

Therefore, blindly applying an 80:20 ratio to every rupee collected may not produce the correct result.

Every collection needs to answer three questions:

What has the borrower paid?

Against which obligation has it been appropriated?

How much belongs to each participating lender?

This is where a well-managed co-lending operation distinguishes itself from a simple loan-sharing arrangement.

And Then Comes Reconciliation

Once collections start moving, another banking discipline becomes critical — reconciliation.

The customer-facing lender may maintain the servicing position.

Each participating lender maintains its own financial exposure.

Collections move through the agreed banking arrangements.

Accounting entries are passed independently by the participating institutions.

All these positions must ultimately agree.

If the borrower has paid ₹5 lakh, one lender cannot recognise a reduction while the other continues to show the old exposure.

Similarly, differences in principal, accrued interest, overdue amounts or collections cannot remain unresolved indefinitely.

Co-lending therefore creates a continuing requirement for reconciliation rather than merely a month-end accounting exercise.

What Happens When the Borrower Does Not Pay?

This is where co-lending becomes even more interesting from a risk-management perspective.

Suppose an instalment becomes overdue.

Which lender identifies the default?

Who communicates it to the other lender?

How quickly?

What Days Past Due should each lender recognise?

What happens when the account moves into SMA or NPA classification?

A shared credit exposure cannot be effectively managed if one participating lender considers the account regular while the other considers the same underlying co-lending exposure stressed.

Timely exchange of delinquency and asset-classification information therefore becomes an essential part of the relationship.

In other words, co-lending requires not only financial synchronisation, but also risk synchronisation.

Recovery Raises a Different Set of Questions

When an account becomes seriously stressed, another practical issue arises.

Who pursues the borrower?

It would make little operational sense for two lenders to independently call the same borrower, issue conflicting instructions or initiate uncoordinated recovery action.

The co-lending arrangement therefore needs clarity regarding who leads collections and recovery.

But leading the recovery does not mean owning the entire decision.

Important decisions may require consultation or consent between lenders — restructuring, settlement, legal proceedings, enforcement of security, waiver, write-off or compromise.

The operating principle should therefore be clear:

One lender may lead the recovery process, but the economic interests and agreed decision rights of both lenders must be protected.

Recoveries Must Again Be Distributed

Suppose a stressed loan with ₹50 lakh outstanding ultimately produces a recovery of ₹30 lakh.

The question is not merely whether ₹30 lakh has been recovered.

Bankers must also determine:

What portion represents principal?

What portion represents interest?

Were recovery or legal expenses incurred?

How should those expenses be borne?

What amount belongs to each lender?

Does the recovery follow the original participation ratio, or are there other contractual considerations?

Once again, the same basic co-lending principle emerges:

A borrower-level transaction ultimately has to be translated into lender-level financial positions.

Collateral Cannot Be Forgotten

For secured loans, co-lending introduces another important dimension.

There may be one property, vehicle, plant or other security supporting a loan in which two lenders have economic interests.

The security therefore needs to be understood in the context of the overall exposure as well as the respective lender positions.

Bankers need continuing visibility over valuation, insurance, creation and perfection of charge, enforceability and eventual release of security.

The position becomes even more important during recovery.

Who initiates enforcement?

Who controls the security documents?

How are enforcement expenses shared?

How are sale proceeds distributed?

Collateral governance in co-lending therefore cannot be separated from exposure governance.

Even Loan Closure Requires Coordination

In conventional lending, when all dues are recovered, the account can normally proceed towards closure and release of security.

Under co-lending, one additional question needs to be answered:

Have both lenders been completely settled?

A borrower may have paid everything due, but there may still be an unsettled amount between the participating lenders.

Therefore, a co-lending relationship should ideally reach closure only when:

the borrower’s obligation is fully settled;

both lender exposures have been extinguished;

all collections have been distributed;

inter-lender settlements are complete;

reconciliation differences have been resolved; and

the security can be appropriately released.

Only then has the complete economic lifecycle ended.

Co-Lending Is Ultimately About Maintaining Multiple Views of the Same Loan

From a banker’s perspective, perhaps the simplest way to understand co-lending is through four questions that need to be answered throughout the life of every loan:

1. Borrower Position — What does the borrower owe?

2. Lender Position — How much of that exposure belongs to each lender?

3. Cash-Flow Position — What has been received and how has it been distributed?

4. Risk Position — How is the underlying exposure performing and classified?

If these four positions remain aligned, co-lending can operate smoothly.

If they begin to diverge, operational, accounting, customer-service and regulatory issues can quickly emerge.

From Loan Sharing to Lifecycle Management

Co-lending should therefore not be viewed simply as:

“Bank A funds 20% and Bank B funds 80%.”

That is only the starting point.

The co-lending model is illustrated hereunder:

Article content

As co-lending portfolios grow, the challenge for banks will increasingly shift from entering into co-lending arrangements to managing them efficiently throughout their lifecycle.

The institutions that do this well will need clear allocation of responsibilities, disciplined information sharing, transparent lender-wise exposure tracking, robust collection distribution, synchronised risk monitoring and strong reconciliation.

The borrower may experience one loan.

But behind that loan are two balance sheets, two risk positions and a continuing financial relationship between the participating lenders.
0

Sustainability & Collateral Management – Vehicles

Vehicles as Collateral: What ESG Information Should Banks Capture?

Vehicle finance represents one of the most widespread forms of secured lending—from personal cars and two-wheelers to commercial fleets, buses, trucks and specialised industrial vehicles.

Traditionally, banks assess vehicle collateral through parameters such as make, model, age, registration, ownership, insurance, market value and depreciation.

These remain fundamental. But as sustainability considerations become increasingly relevant to financial institutions, another question emerges:

Should banks also understand the sustainability characteristics of the vehicles they finance and hold as collateral?

In our opinion, increasingly yes—but the assessment needs to remain practical, proportionate and relevant to lending and collateral risk.

Vehicle ESG Assessment Is More Than EV vs ICE

The first sustainability distinction that comes to mind is usually:

Electric Vehicle or Internal Combustion Engine Vehicle?

That is important, but it is only the starting point.

Two diesel commercial vehicles of similar age and value may have very different emission standards, fuel efficiency, utilisation patterns and remaining economic lives.

Similarly, two electric vehicles may differ significantly in battery technology, battery health, remaining warranty, charging compatibility and expected residual value.

For a banker, the sustainability framework should therefore focus on information that could influence the vehicle’s economic life, regulatory acceptability, operating viability, marketability and residual value.

What Information Should Banks Capture?

I believe a common vehicle sustainability dataset should cover the following broad areas:

  • Vehicle Identity & Classification
  • Propulsion & Fuel Technology
  • Emission & Environmental Performance
  • Energy / Fuel Efficiency
  • Vehicle Age & Remaining Useful Life
  • Regulatory & Environmental Compliance
  • Safety & Social Parameters
  • Insurance & Climate Protection
  • Maintenance & Operating Condition
  • End-of-Life & Circularity
  • Green / Sustainable Finance Classification
  • ESG & Sustainability Risk Indicators

The detailed data requirement can then vary according to whether the financed asset is a personal vehicle, commercial vehicle, fleet or specialised industrial vehicle.

Personal Vehicles: Keep It Proportionate

For a personal car or two-wheeler loan, an extensive ESG questionnaire would neither be practical nor proportionate.

The bank can concentrate on a relatively small dataset covering:

  • Fuel/propulsion type
  • Emission standard
  • Fuel or energy efficiency
  • Vehicle age
  • EV battery information, where applicable
  • Insurance
  • Regulatory compliance
  • Green vehicle classification

Much of this information may already be available through vehicle documentation and the loan-origination process.

The objective should therefore be data enrichment—not additional customer paperwork.

Commercial Vehicles Require Deeper Assessment

The sustainability dimension becomes considerably more important for trucks, buses, taxis, delivery vehicles and commercial fleets because their utilisation and environmental footprint can be substantially higher.

In addition to the common dataset, banks may consider information relating to:

  • Annual kilometres travelled
  • Fuel consumption
  • Load/capacity utilisation
  • Emission performance
  • Maintenance history
  • Fleet age
  • Route and operating profile
  • Alternative-fuel readiness

At the fleet level, the bank can potentially derive indicators such as EV share, low-emission vehicle share, average fleet age, fuel mix and fleet transition progress.

This begins to convert individual collateral data into meaningful portfolio intelligence.

Industrial & Special-Purpose Vehicles Need Another Layer

The same questionnaire cannot reasonably assess a passenger car, an excavator and a large mining dumper.

Industrial and specialised assets such as excavators, loaders, cranes, forklifts, construction equipment, mining vehicles and agricultural equipment require additional consideration of:

  • Engine and propulsion technology
  • Fuel consumption
  • Operating hours
  • Energy efficiency
  • Emission standards
  • Equipment age
  • Maintenance condition
  • Remaining economic life
  • Availability of lower-emission alternatives

This reinforces an important principle:

Vehicle sustainability assessment should be asset-category driven.

EVs Introduce a New Collateral Dimension—the Battery

For electric vehicles, the battery can represent a significant component of both the vehicle’s economic value and sustainability profile.

Banks may therefore progressively need visibility into:

Battery Type | Capacity | Age | Health | Remaining Warranty | Ownership | Replacement Economics | Recycling / Second-Life Potential

Over time, battery condition could become relevant not only to ESG assessment but also to vehicle valuation and residual-value estimation.

Safety Is Also Part of ESG

Vehicle sustainability should not be viewed only through the environmental lens.

The Social dimension can include vehicle and operator safety.

Depending upon the vehicle category, relevant information may include safety rating, mandatory safety features, accident history, fitness certification, inspection status and driver-assistance systems.

For buses, trucks and industrial vehicles, operational safety assumes even greater importance.

Don’t Create Another Manual Data-Collection Exercise

One of the most important design principles should be:

Do not ask the borrower to provide information that the bank can reliably obtain elsewhere.

Vehicle sustainability information can potentially be assembled from:

  • Loan origination data
  • Vehicle registration and documentation
  • Manufacturer specifications
  • Insurance information
  • Inspection and valuation data
  • Commercial-fleet telematics
  • External databases / APIs
  • Customer-reported information
  • System-derived calculations

The collateral management platform should progressively bring this information together, rather than create another standalone questionnaire.

From Individual Vehicles to Portfolio Intelligence

Once structured sustainability information becomes available, banks can potentially analyse their vehicle collateral portfolios across dimensions such as:

  • EV versus ICE exposure
  • Fuel-type distribution
  • Emission-standard distribution
  • Average age of vehicle collateral
  • High-emission vehicle exposure
  • Green vehicle financing
  • Battery-related collateral exposure
  • Commercial fleet transition risk
  • Vehicles approaching technological or economic obsolescence

This is where sustainability data begins to move from data collection to risk intelligence.

The Banker’s Perspective: Proportionality Matters

The purpose should not be to transform every vehicle loan into a complex ESG assessment.

A practical framework could follow:

Personal Vehicle → Lightweight Sustainability Dataset

Commercial Vehicle → Enhanced ESG + Utilisation Dataset

Fleet Finance → Vehicle + Portfolio Sustainability Assessment

Industrial / Special-Purpose Vehicle → Equipment-Specific ESG Assessment

The depth of assessment should reflect the nature, value, usage, environmental impact and risk characteristics of the financed asset.

From Vehicle Value to Vehicle Resilience

Traditional vehicle collateral management asks:

“What is this vehicle worth today?”

A sustainability-enabled framework introduces additional questions:

How efficient is the vehicle?

How environmentally and regulatorily compliant is it?

How long will its technology remain economically viable?

Could transition towards cleaner technologies accelerate its depreciation?

Could these factors influence its future marketability and residual value?

Ultimately, the more relevant question for the lender may become:

“How resilient is the value of this vehicle over the remaining life of the bank’s exposure?”

That is where sustainability becomes relevant to collateral management.

The objective is not ESG data collection for its own sake.

It is a gradual progression from:

Collateral Identification → Valuation → Monitoring → Sustainability Assessment → Collateral Resilience

This is Series 3 of Sustainability in Collateral Management.

I am sharing this as a generic working framework with the broader banking, vehicle-finance, risk, ESG, sustainability and collateral-management community rather than as a prescribed methodology.

Views and practitioner perspectives on what additional sustainability information banks should consider for vehicle collateral would be most welcome.

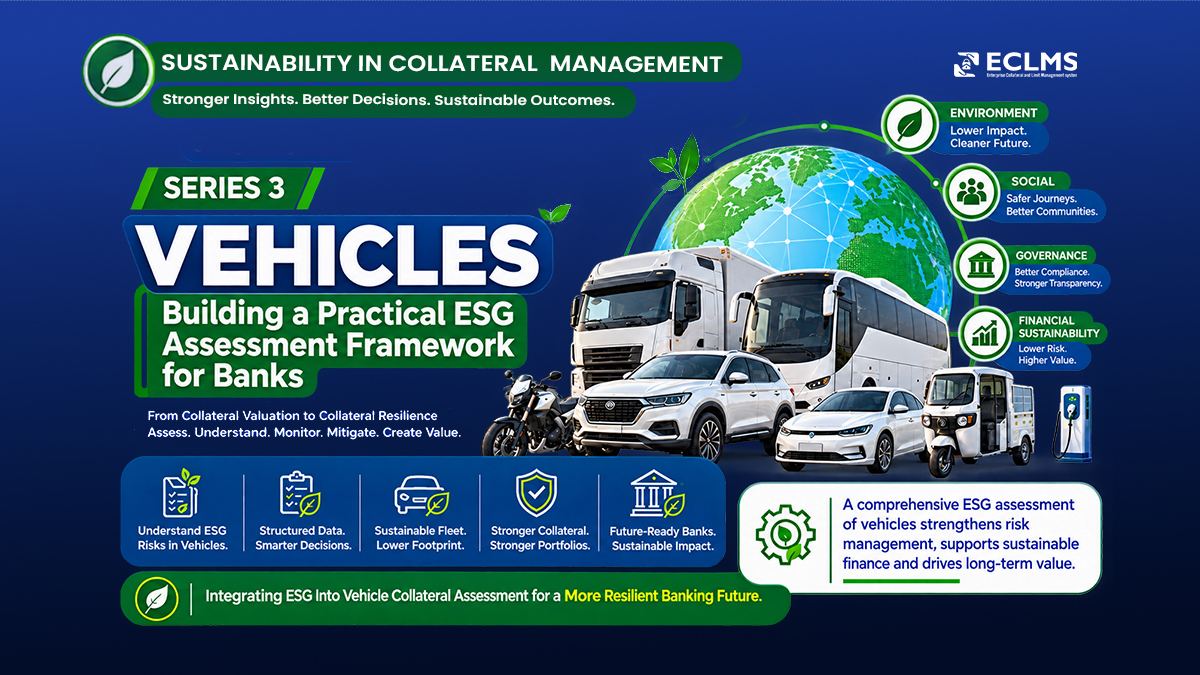
An overall snapshot summarises the proactive approach to vehicle finance vis a vis sustainable finance.

Article content

#CollateralManagement #VehicleFinance #ESG #Sustainability #Banking #ElectricVehicles #CommercialVehicles #GreenFinance #RiskManagement #ClimateRisk

1

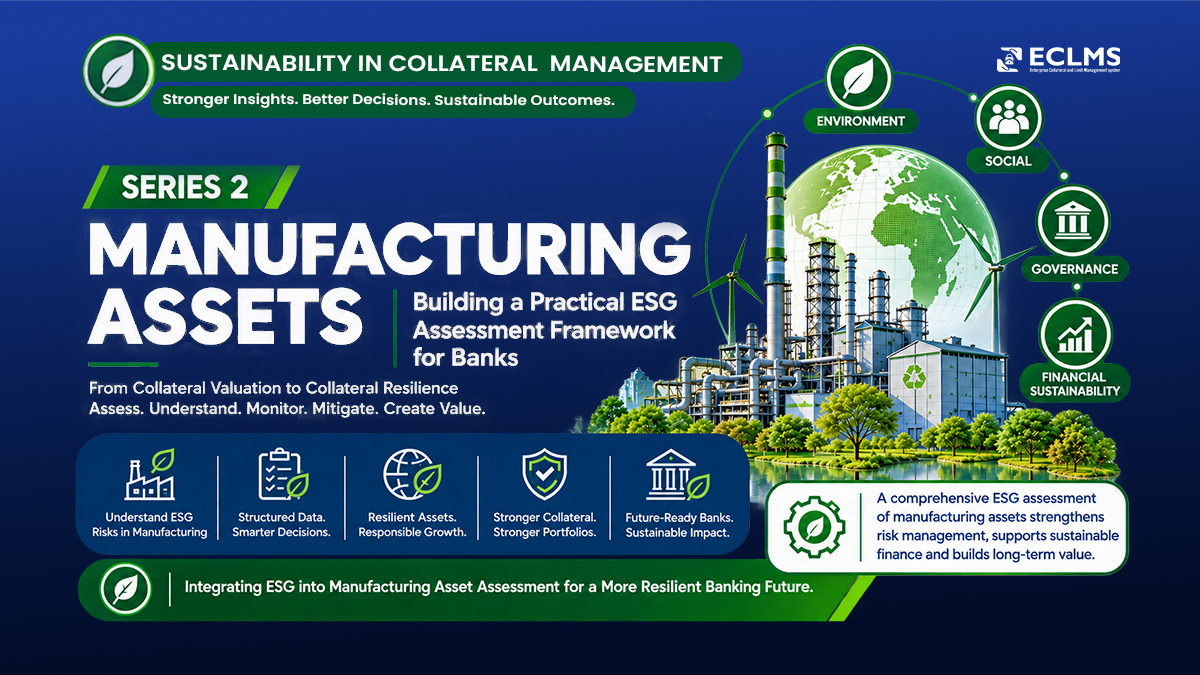
Sustainability in Collateral Management – Manufacturing Assets

Sustainability in Collateral Management - Manufacturing Assets

In the first article of this series, we discussed the need to look beyond the conventional legal and financial characteristics of property collateral and progressively build a sustainability profile of the underlying asset.

Banks are indirectly involved in various manufacturing activities through funding; therefore, ascertaining sustainability aspects is critical when orienting their funds towards environment friendly activities. Evaluating sustainability in respect of manufacturing assets presents a significantly more complex challenge.

A manufacturing facility cannot be assessed only by asking whether the building is energy efficient, exposed to flooding, adequately insured or environmentally compliant.

The industrial activity taking place within that property can itself materially influence the sustainability and risk profile of the collateral.

A steel plant, pharmaceutical unit, automobile factory, textile processing facility and food-processing plant may all be classified broadly as manufacturing assets—but their environmental footprint, resource dependencies, regulatory requirements and transition risks can be substantially different.

From a banker’s perspective, this raises an important question:

How do we build a manufacturing sustainability assessment that is comprehensive without creating hundreds of different questionnaires?

A Layered Approach to Manufacturing ESG Assessment

In our view, the solution lies in a layered data architecture.

Instead of attempting to design one universal questionnaire—or a completely separate questionnaire for every industry—the assessment can be progressively constructed through four layers:

1. Common Manufacturing ESG Dataset: A baseline dataset applicable to manufacturing facilities irrespective of the industry.

2. Industry Group-Specific Dataset: Additional parameters based on the broad nature of the manufacturing activity—for example, metals, chemicals, automotive, textiles or food processing.

3. Industry / Activity-Specific Dataset: Specialised parameters relevant to the actual manufacturing process.

4. Site & Location-Specific Risk Dataset: Physical climate and environmental risks associated with the geographical location of the facility.

The resulting assessment can therefore be represented conceptually as:

Manufacturing ESG Assessment = Common Manufacturing Data + Industry-Specific Data + Activity-Specific Data + Site/Climate Risk

What Should the Common Manufacturing Dataset Cover?

Before getting into industry-specific requirements, Indian banks need a consistent baseline. The common manufacturing ESG dataset that we have been working on covers the following major areas:

The accompanying infographic provides an illustrative view of the data points that may be considered within these areas.

Article content

Why This Matters to a Banker

For banks, sustainability data should ultimately contribute to better risk understanding rather than becoming another compliance-oriented data collection exercise.

A structured manufacturing sustainability profile can potentially support:

• Identification of environmentally sensitive collateral

• Assessment of physical climate vulnerability

• Identification of energy-, water- and carbon-intensive assets

• Monitoring of environmental clearances and regulatory compliance

• Assessment of transition risk

• Identification of green or transition-finance opportunities

• Monitoring of climate-related insurance protection

• Portfolio concentration analysis across ESG-sensitive industries

• Identification of assets requiring enhanced monitoring

• Future assessment of sustainability implications for collateral value and marketability

Absolute Numbers Alone May Not Tell the Story

Manufacturing assessment also requires greater emphasis on intensity metrics.

A large manufacturing facility will naturally consume more electricity, water and other resources than a smaller facility.

Therefore, recording only absolute consumption may not provide a meaningful basis for comparison.

Where appropriate, the framework should also derive measures such as:

Energy Intensity = Energy Consumption / Production Output

Water Intensity = Water Consumption / Production Output

Carbon Intensity = GHG Emissions / Production Output

This enables comparison across facilities and, more importantly, monitoring of improvement or deterioration in the sustainability performance of the same asset over time.

Data Collection Should Not Mean Manual Data Entry

Another important consideration is the source of sustainability information.

Not every data point should be manually entered.

A mature collateral sustainability framework should progressively distinguish between:

• Customer / User Reported Data

• Document-Sourced Data

• Existing Bank / Collateral Data

• External API / GIS-Sourced Data

• System-Calculated Data

For example, production and energy-consumption information may come from the customer or supporting documents, while flood, cyclone, earthquake, heat stress or water-stress exposure can increasingly be obtained from external geospatial sources.

Carbon intensity, water intensity and composite risk indicators can then be system-calculated.

This approach can substantially improve both the reliability and operational feasibility of ESG data collection.

Entity ESG Risk and Asset Sustainability Risk Are Different

As discussed in Series 1, this distinction becomes even more important for manufacturing.

A manufacturing company may have a corporate ESG rating, but an individual plant offered as collateral can have its own sustainability characteristics.

The plant may be:

• located in a water-stressed region,

• dependent on carbon-intensive energy,

• exposed to flooding,

• operating under environmental clearances approaching expiry,

• generating hazardous waste, or

• operating with significantly better sustainability characteristics than the borrower’s other facilities.

Therefore:

Borrower ESG Profile ≠ Individual Manufacturing Asset Sustainability Profile

Banks may ultimately need visibility into both.

From Collateral Valuation to Collateral Resilience

Traditional collateral management asks:

What is the asset worth today?

A sustainability-enabled collateral framework introduces additional questions:

How environmentally sustainable is the asset?

How exposed is it to physical and transition risks?

Could these risks influence its future operations, insurability, marketability or value?

And perhaps most importantly:

How resilient is the collateral over the remaining life of the bank’s exposure?

This is where we believe sustainability can become an important additional dimension of modern collateral management.

The objective should not be to turn the collateral management system into a full-scale enterprise ESG platform.

Rather, it should ensure that sustainability characteristics capable of materially affecting collateral risk are identified, structured, monitored and made available to the bank’s wider risk-management ecosystem.

#CollateralManagement #ESG #Sustainability #Manufacturing #ClimateRisk #Banking #RiskManagement #GreenFinance #SustainableFinance #ClimateResilience

0

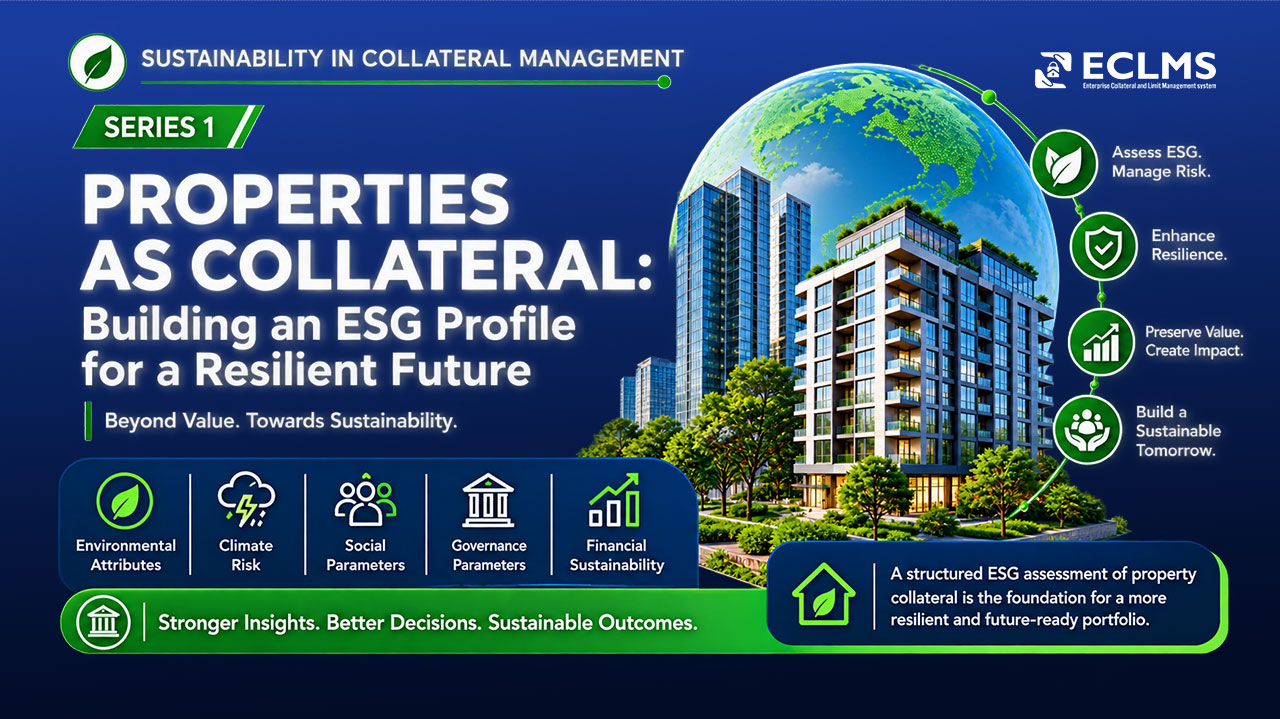
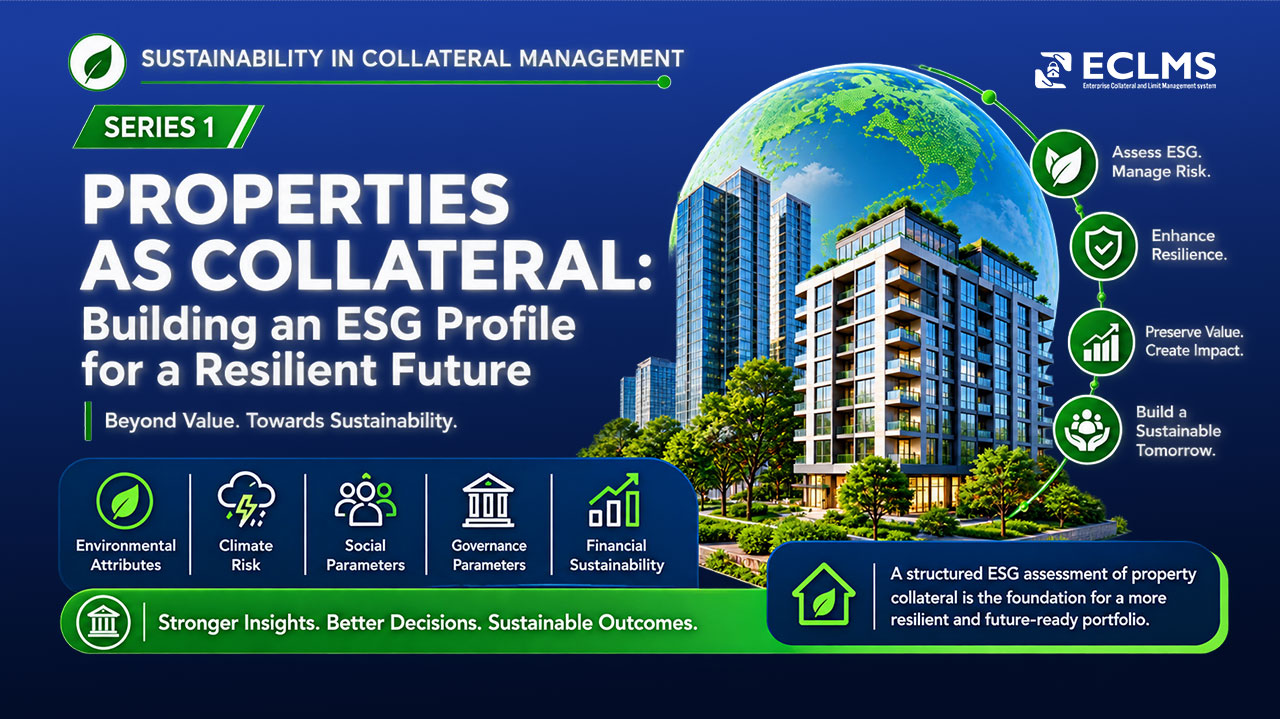
Sustainability in Collateral Management — Series 1

For decades, banks have assessed property collateral primarily through a familiar set of parameters—ownership, title, valuation, location, marketability, legal enforceability and insurance.

But the risk environment surrounding physical assets is changing.

A property may have a strong market value today, but its long-term value, marketability, insurability and resilience could increasingly be influenced by environmental and climate-related factors.

Consider a few questions:

  • Is the property exposed to flooding?
  • Is it located in an area vulnerable to cyclones, earthquakes, wildfires or rising sea levels?
  • How energy-efficient is the building?
  • Does it have a recognised green-building certification?
  • Could environmental litigation or regulatory non-compliance affect its value?
  • Is adequate insurance available against material climate events?

These questions suggest that collateral management may need to evolve beyond maintaining a static financial and legal description of an asset.

Building a Sustainability Profile of Your Collateral

For properties and physical assets, we believe a structured ESG assessment should consider data across five broad dimensions:

  1. Environmental Attributes
  2. Climate Risk
  3. Social Parameters
  4. Governance Parameters
  5. Financial Sustainability

The accompanying infographic provides an illustrative framework of the data points that banks may consider capturing under these dimensions.

A structured sustainability dataset can potentially help banks develop capabilities for:

  • Climate vulnerability assessment
  • ESG risk profiling
  • Green asset identification
  • Sustainability-linked financing assessment
  • Climate insurance monitoring
  • Portfolio-level sustainability analytics
  • Identification of collateral exposed to emerging environmental and climate risks

Borrower ESG Risk and Collateral Sustainability Risk Are Not the Same

An important distinction needs to be made between Borrower ESG Risk and Collateral Sustainability Risk.

A borrower may have a strong corporate ESG profile, while a particular property offered as collateral may still be located in a high flood-risk zone, have poor energy efficiency or face other environmental vulnerabilities.

Conversely, an individual asset may have strong sustainability characteristics even when the broader ESG profile of the borrower requires improvement.

Therefore, the sustainability profile of collateral deserves to be assessed as a distinct—but interconnected—dimension of enterprise risk and collateral management.

The Question for Banks Is Changing

As banks progressively strengthen their ESG and climate-risk frameworks, the question may no longer be only:

“What is the current value of my collateral?”

It may increasingly become:

“How sustainable and climate-resilient is my collateral—and what could that mean for its value over the life of the exposure?”

This is the first article in my series on Sustainability in Collateral Management.

In the next article, we will discuss the significantly more complex challenge of ESG assessment of manufacturing and industrial assets, including how a common manufacturing ESG dataset can be supplemented with industry-specific sustainability parameters.

#CollateralManagement #ESG #Sustainability #ClimateRisk #Banking #RiskManagement #GreenFinance #SustainableFinance

0

Why Risk Management Is About to Get Non-Negotiable for Indian Banks and NBFCs

Risk Management in Indian Banks and NBFC's
Risk  management for Indian banks and NBFC's

Indian financial institutions are entering the most consequential regulatory reset since the 1990s prudential norms — and most risk teams are not ready for what’s coming. 

In April 2026, the RBI issued its final directions on Expected Credit Loss (ECL) provisioning for Scheduled Commercial Banks, replacing the decades-old incurred-loss, overdue-ageing model with a forward-looking, IFRS 9-aligned framework. Banks now have until April 1, 2027 to implement it, with a glide path to absorb the capital impact stretching out to 2031. NBFCs and large corporates have already been living under this regime — via Ind AS 109 — for years. Banks are the last major regulated entities left to make the jump, and the runway is tight. 

Layer on top of that RBI’s Large Exposures Framework, which caps a bank’s exposure to any single counterparty at 20% of Tier 1 capital (25% for a group of connected counterparties), with any breach requiring board-level sign-off and mandatory rectification within 30 days. And add tightened intragroup exposure norms for foreign bank branches effective April 2026. The message from the regulator is consistent: institutions need real-time, defensible visibility into exposure and collateral — not quarter-end reconciliation. 

Why This Is Personal for Indian Risk Teams 

India doesn’t need to import case studies to make the point. The IL&FS collapse in 2018 and the DHFL crisis that followed were, at their core, concentration and collateral failures — infrastructure and housing finance exposures that looked diversified on paper but were opaque, interconnected, and poorly collateralized in reality. Both triggered contagion through the NBFC sector and mutual fund holdings, and both are still cited by regulators and rating agencies as the reason India’s large exposure and provisioning norms exist in their current form. 

That history is exactly why the ECL shift matters more here than almost anywhere else. A model built on forward-looking probability of default, loss given default, and exposure at default would have flagged IL&FS-style deterioration long before the overdue-ageing model did. The RBI’s own framing is unambiguous: banks have effectively been fighting fires after the house burns down; ECL asks them to price the fire risk before it starts. 

What This Means Operationally 

For risk and credit teams at Indian banks, NBFCs, trade finance houses, and commodity trading desks, the next 18 months mean building — or buying — the infrastructure to support: 

  • Counterparty and group-level limit monitoring mapped directly to LEF thresholds (20%/25% of Tier 1 capital), with automated alerts well before a breach, not a scramble to explain one to the RBI within the 30-day window 
     
  • PD/LGD/EAD modelling with a minimum of five years of clean historical data — a genuine problem for institutions still running fragmented, spreadsheet-based exposure records 
     
  • Board-level governance and model validation frameworks, since RBI’s final directions explicitly require model inventories and structured oversight, not just a provisioning number 
     
  • Real-time collateral valuation integrated with exposure data, because Stage 1/Stage 2 classification under ECL depends on early signs of credit deterioration that static, quarterly collateral marks will simply miss 
     
  • MSME-specific monitoring, since RBI’s own commentary flags MSMEs and smaller borrowers as the segment where ECL implementation will require the closest watching — thinner credit histories make PD estimation harder and provisioning swings sharper 

The Two-Tier Problem Nobody’s Talking About Yet 

One detail getting less attention than it deserves: RBI’s ECL directions exclude Regional Rural Banks, Small Finance Banks, and Payments Banks — for now. That creates a two-tier system where the largest, most sophisticated players move to forward-looking risk models while smaller, often more vulnerable institutions stay on the old ageing-based approach. Anyone building a limit and collateral management strategy right now should be building for eventual convergence, not just the April 2027 deadline in front of them. 

Bringing Limits and Collateral Onto One Platform 

None of this is achievable through disconnected spreadsheets and manual reconciliation — not at the data granularity RBI is now asking for. Institutions that centralise exposure, limits, and collateral data onto a single, real-time platform get: 

  • A single view of counterparty and group exposure, mapped directly to LEF limits 
  • Automated breach alerts that give teams the runway to act inside the 30-day rectification window 
  • Audit trails and model governance documentation built for RBI’s board-oversight and validation requirements, not retrofitted after the fact 
  • API-based integration with existing core banking and treasury systems, avoiding a rip-and-replace implementation during an already tight regulatory runway 

The Bottom Line 

The ECL transition, the tightened Large Exposures Framework, and the lessons of IL&FS and DHFL all point to the same conclusion: limit management and collateral management are no longer back-office housekeeping in India. They are the mechanism that determines whether an institution meets RBI’s April 2027 deadline with confidence or scrambles through it. 

If your institution is mapping out its ECL and LEF readiness, our team can walk you through how an enterprise-grade limit and collateral management platform fits into that roadmap — with minimal disruption to your existing core systems. 

Get in touch to schedule a walkthrough built specifically around India’s evolving risk and provisioning landscape. 

1

The Hidden Compliance Risks Of manual Limit Monitoring

The Hidden Compliance Risks Of manual Limit Monitoring
Risks Of  manual Limit Monitoring in banking

Spreadsheets, reminder emails, and shared trackers may feel manageable — until they aren’t. As regulatory scrutiny intensifies and penalty volumes climb, the hidden costs of manual limit monitoring are becoming impossible to ignore. 

$19.3B 

Global regulatory fines in 2024 — a record high 

417% 

Surge in financial penalties in H1 2025 vs. H1 2024 

74% 

Of compliance failures attributed to human error 


The problem 

When “good enough” becomes a liability 

For years, compliance teams have relied on manual processes — spreadsheets, calendar alerts, and shared documents — to track thresholds, exposure limits, and regulatory caps. These tools are familiar, low-cost, and easy to deploy. They’re also dangerously fragile. 

The scale of the problem is no longer academic. Global regulatory fines hit a record-breaking $19.3 billion in 2024, driven by enforcement actions across AML, sanctions, consumer protection, and transaction monitoring. Penalties specifically targeting banks surged 522% to $3.65 billion — and AML-related enforcement alone exceeded $3.3 billion, a 100% year-over-year increase. The trajectory in 2025 is even steeper: regulatory fines against financial institutions jumped 417% in the first half of the year compared to the same period in 2024. 

Embedded in many of these enforcement actions is a pattern regulators find particularly damning: firms that knew about risks but lacked the systems to act on them in time. 

 
“Manual compliance processes remain one of the biggest obstacles to maintaining effective compliance programs.” 
 
— Wolters Kluwer Compliance Analytics, 2024 

 
Four hidden risks 

Where manual monitoring quietly fails 

Manual limit monitoring doesn’t fail dramatically — it fails in increments. A missed cell update. A reporting cycle that runs a day late. A limit that was accurate last quarter but hasn’t been refreshed since the regulation changed. Here are the four risk vectors organizations consistently underestimate. 

 
1. Human error compounds silently 

Human error accounts for 74% of compliance failures. Spreadsheet mistakes go undetected because manual auditing catches errors at a rate of only 56% — and conventional error-checking tools perform far worse. 

2. Latency in breach detection 

Manual processes are point-in-time, not continuous. By the time a limit breach surfaces in a weekly report, the window for remediation may have already closed — and regulators rarely accept “we didn’t know in time.” 

3. Fragmented oversight, fragmented evidence 

Compliance teams operating across multiple tools and platforms struggle to produce clean audit trails. Fragmented systems create redundancies, delay investigations, and make it difficult to access real-time insights during examinations. 

4. Complexity grows; capacity doesn’t 

Multi-jurisdictional rules, frequent regulatory updates, and expanding product lines create compliance complexity that scales exponentially. Manual tracking capacity remains linear — creating an impossible gap as operations grow. 

The enforcement environment has fundamentally shifted 

The assumption that regulators will accept good-faith manual efforts as a defense has eroded significantly. In several high-profile 2024 enforcement actions, institutions were penalized not only for the underlying violations but for failing to maintain compliance programs commensurate with their risk profiles — even when the violations were caught internally. 

Transaction monitoring failures 

Penalties for transaction monitoring breaches — a category closely linked to manual reporting gaps — exceeded $3.3 billion in 2024, representing a 100% year-over-year increase. In one case, a firm received multiple fines in a single year for failing to report transactions over regulatory thresholds despite having flagged them internally. 

AML and KYC violations 

Global financial institutions faced over $263 million in AML and KYC fines in the first half of 2024 alone — a 31% increase from the prior year. Inadequate customer due diligence and failures to update risk assessments were recurring findings, both of which frequently trace back to manual, periodic review cycles. 

Third-party and vendor limits 

As regulators sharpen focus on third-party risk management, the ability to continuously monitor vendor-related exposure limits has become a compliance requirement, not a best practice. Firms managing hundreds of third-party relationships via spreadsheets face structural exposure that is difficult to defend in an examination. 
 

Non-compliance costs 2.71× more than prevention 

Research analyzing the 12 largest regulatory penalties between 2023 and 2025 found that non-compliance costs organizations 2.71 times more than maintaining robust compliance programs. When legal fees, remediation costs, operational disruption, and reputational damage are factored in, the calculus becomes stark. 

Manual processes also impose a quieter cost: time. Organizations relying on manual compliance workflows can expect to lose 28 or more hours per week to tasks that automated systems can handle with fewer errors and greater consistency. That capacity drain compounds over time, crowding out the higher-judgment work that experienced compliance professionals are uniquely equipped to perform. 

According to the National Institute of Standards and Technology (NIST), automated monitoring allows organizations to track more compliance metrics with fewer resources — and with meaningfully greater reliability than manual methods. Automation, in the right context, can reduce human error by up to 90%. 

Moving from reactive to continuous 

The shift away from manual limit monitoring is not primarily a technology decision — it’s a risk governance decision. Organizations that have reduced enforcement exposure share a common structural pattern: they treat limit monitoring as a continuous, system-level function rather than a periodic human task. 

Effective frameworks typically combine real-time monitoring feeds with automated alerting at configurable thresholds, integrated audit trails that generate examination-ready documentation, and clear escalation pathways that reduce the latency between detection and response. Critically, they also maintain human oversight for judgment calls — automation handles volume and speed; experienced compliance officers handle interpretation and decision-making. 

The financial services industry is already moving in this direction. According to Protiviti’s 2025 compliance priorities analysis, 41% of financial services firms surveyed in 2024 expect to spend more than 10% of their digital budgets on generative AI alone — much of it oriented toward compliance, monitoring, and risk detection functions. The institutions that invest in this infrastructure now are building a defensible posture for an enforcement environment that shows no signs of softening. 
 

The question is no longer whether manual monitoring carries compliance risk. The question is how much risk your organization is prepared to carry — and what a single enforcement action would cost compared to the infrastructure that could have prevented it. 

0

Collaterals in the New ECL-Based IRAC Framework

the Importance of Collateral Management Has Increased in the RBI’s Evolving Credit Risk Architecture
Why the Importance of Collateral Management Has Increased in the RBI’s Evolving Credit Risk Architecture 

1. Introduction

The transition of the Indian banking sector from the traditional prudential Income Recognition and Asset Classification (IRAC) framework to the Expected Credit Loss (ECL)-based impairment regime represents one of the most significant transformations in credit risk management in recent decades. The revised framework introduced by the Reserve Bank of India fundamentally changes the manner in which banks recognize stress, estimate losses, classify assets, and maintain provisions against credit exposures.

Much of the industry discourse around the new framework has focused on:

  • Probability of Default (PD),
  • Loss Given Default (LGD),
  • Exposure at Default (EAD),
  • staging methodology,
  • macroeconomic overlays,
  • and forward-looking provisioning models.

However, amidst these discussions, a critical misconception has started emerging across banking and technology circles — the assumption that collateral management may lose significance in the new ECL-based IRAC environment because traditional “security erosion” rules may no longer remain central to asset classification.

This perception is fundamentally incorrect.

In reality, the ECL framework significantly increases the strategic importance of collateral management. What changes is not the relevance of collateral, but the manner in which collateral influences risk assessment and provisioning.

Under the legacy IRAC architecture, collateral was largely viewed as a prudential support mechanism. Under the ECL regime, collateral becomes a core risk parameter driving expected recoverability and loss estimation.

This transformation requires banks to completely rethink the design, governance, valuation, monitoring, and technological integration of collateral management systems.

The future banking environment will no longer permit collateral systems to function merely as operational repositories maintaining charge records and valuation dates. Instead, collateral management must evolve into an intelligent, continuously monitored, analytically driven risk management ecosystem integrated deeply with enterprise credit risk architecture.

The institutions that fail to recognize this transformation may face serious challenges in:

  • ECL accuracy,
  • provisioning adequacy,
  • model validation,
  • supervisory assessments,
  • and portfolio risk visibility.

Conversely, banks that redesign collateral management as an enterprise risk intelligence capability will gain substantial advantages in:

  • credit monitoring,
  • early warning detection,
  • capital optimization,
  • recovery estimation,
  • and risk-adjusted profitability.

2. Traditional Role of Collateral Under Existing IRAC Norms

To understand the transformation underway, it is important first to understand the traditional role collateral played under the existing IRAC framework.

Historically, the prudential framework in India followed a largely rule-based approach toward asset classification and provisioning. Asset quality deterioration was primarily recognized based on:

  • Days Past Due (DPD),
  • default events,
  • restructuring events,
  • prudential supervisory triggers,
  • and specified regulatory conditions.

Within this architecture, collateral primarily served four broad purposes:

A. Credit Risk Mitigation

Collateral provided secondary repayment support in case borrower cash flows failed.

B. Prudential Provisioning Support

Availability of security enabled differentiated provisioning treatment between secured and unsecured portions of exposures.

C. Regulatory Asset Classification Triggers

Specific prudential rules such as “security erosion” could directly impact asset classification.

D. Recovery Support

Collateral acted as a legal enforcement and recovery mechanism after default.

Among these, the “security erosion” concept became one of the most prominent regulatory mechanisms influencing collateral management practices.

Under traditional IRAC guidelines:

  • where the realizable value of security declined below specified thresholds,
  • banks were required to accelerate asset classification deterioration irrespective of repayment conduct.

For example:

  • if the realizable value of security fell below 50% of assessed value, the account could be straightaway classified as doubtful,
  • if realizable value fell below 10% of outstanding, the exposure could be identified as a loss asset.

This framework resulted in collateral systems being designed primarily as compliance-oriented utilities.

Accordingly, most banking collateral management systems focused on:

  • periodic valuation tracking,
  • security coverage computation,
  • document management,
  • charge registration,
  • margin monitoring,
  • and prudential reporting.

The operational question under the old regime was relatively straightforward:

“Has the security erosion threshold been breached?”

If yes, the system triggered supervisory classification consequences.

The approach was therefore:

  • threshold-driven,
  • event-based,
  • and largely binary.

Collateral deterioration was treated as a regulatory event rather than a continuously evolving risk parameter.


3. The Conceptual Shift Introduced by the ECL Framework

The ECL framework fundamentally changes this philosophy.

The new model replaces the traditional “incurred loss” approach with a “forward-looking expected loss” methodology.

Under the incurred loss regime:

  • losses were generally recognized after observable deterioration or default events occurred.

Under ECL:

  • losses are estimated proactively based on future expected recoverability.

This shift is transformational.

The ECL methodology estimates expected losses using three core parameters:

  • Probability of Default (PD),
  • Loss Given Default (LGD),
  • Exposure at Default (EAD).

Among these, collateral has a direct and material influence on LGD.

LGD essentially estimates the economic loss likely to arise if default occurs after considering expected recoveries.

This means collateral now directly affects:

  • expected recovery values,
  • recovery timelines,
  • distress realization estimates,
  • legal recovery costs,
  • and economic recoverability assumptions.

Consequently, collateral becomes embedded within the core mathematics of provisioning itself.

Under the new framework, deterioration in collateral value no longer needs a separate prudential “trigger” to influence provisioning.

Instead:

  • every change in collateral quality dynamically influences expected losses.

This is the most important conceptual transition.

Under old IRAC:

security erosion was a classification event.

Under ECL:

collateral deterioration becomes a continuously evolving risk variable.

This distinction fundamentally changes the design philosophy of collateral management systems.


4. Why Security Erosion Does Not Become Redundant

The emergence of ECL has led some industry participants to assume that since specific “security erosion” downgrade rules may reduce in prominence, collateral management itself may become less important.

This assumption is dangerous and misleading.

The reality is exactly the opposite.

The ECL framework makes collateral management significantly more important because collateral now directly impacts provisioning accuracy.

In the traditional framework:

  • security erosion mattered only after certain thresholds were breached.

Under ECL:

  • every deterioration in collateral quality matters.

For example:

  • decline in property prices,
  • inventory obsolescence,
  • stock market volatility,
  • deterioration in receivable quality,
  • legal disputes,
  • insurance lapses,
  • enforceability challenges,
  • or delays in recovery realization

can all impact expected recoverable value.

These changes directly affect LGD estimation and therefore ECL provisioning.

The provisioning effect therefore becomes:

  • continuous,
  • dynamic,
  • and economically sensitive.

Thus, while simplistic threshold-based “security erosion” rules may gradually lose independent significance, collateral itself becomes far more deeply integrated into the risk measurement process.


5. Collateral as a Core Input in LGD Estimation

The most critical role of collateral in the ECL framework lies in LGD computation.

Loss Given Default represents the proportion of exposure expected to remain unrecovered after default.

Conceptually:

[
LGD = \frac{Exposure – Expected\ Recovery}{Exposure}
]

Expected recovery is heavily dependent upon:

  • collateral quality,
  • realizable value,
  • enforceability,
  • and liquidation efficiency.

Accordingly, collateral management becomes central to:

  • provisioning estimation,
  • model calibration,
  • and portfolio stress assessment.

Unlike traditional provisioning norms, ECL requires banks to estimate:

  • future economic recoveries,
  • distress sale realizations,
  • time value of recovery cash flows,
  • legal recovery delays,
  • enforcement costs,
  • and market volatility.

This significantly elevates the sophistication required in collateral valuation methodologies.

Collateral valuation can no longer remain:

  • static,
  • periodic,
  • or purely compliance-oriented.

Instead, valuation must become:

  • dynamic,
  • risk-sensitive,
  • scenario-based,
  • and forward-looking.

6. Importance of Objective Collateral Valuation

One of the biggest implications of the ECL framework is the increasing need for objective collateral valuation systems.

Historically, many collateral valuations in the banking system relied heavily on:

  • periodic appraisals,
  • standardized haircuts,
  • conservative approximations,
  • and manual assessments.

Such approaches may prove inadequate under ECL.

The new framework requires collateral values to reflect:

  • realistic realizable value,
  • stressed market conditions,
  • liquidity risk,
  • volatility risk,
  • and enforceability uncertainty.

For example:

  • a commercial property in an oversupplied market cannot be valued merely at nominal market rates,
  • inventory financed under supply-chain arrangements may rapidly deteriorate in realizable value,
  • receivables may become impaired due to counterparty weakness,
  • machinery may have low secondary market demand,
  • project assets may suffer severe realization constraints.

Accordingly, collateral valuation systems must increasingly incorporate:

  • market intelligence,
  • distress liquidation modelling,
  • scenario analysis,
  • volatility indicators,
  • and sectoral sensitivity analysis.

This requires a major transformation in collateral governance architecture.


7. Dynamic Monitoring of Collateral

Another major change introduced by the ECL framework is the need for continuous collateral monitoring.

Under traditional systems:

  • collateral values were often reviewed annually or periodically.

Under ECL:

  • collateral quality must be continuously assessed because changes in collateral directly affect provisioning.

Future-ready collateral systems must therefore support:

  • automated revaluation triggers,
  • market-linked valuation updates,
  • volatility monitoring,
  • stress testing,
  • concentration analysis,
  • insurance tracking,
  • legal enforceability monitoring,
  • and exception alerts.

The system must identify:

  • sudden value deterioration,
  • stale valuations,
  • collateral concentration risks,
  • weakening enforceability,
  • and sector-specific vulnerabilities.

This transforms collateral management from a passive administrative function into an active risk surveillance mechanism.


8. Data Quality Becomes Critically Important

The ECL framework dramatically increases the importance of collateral data quality.

Under earlier IRAC systems, incomplete collateral information may still have allowed operations to continue because provisioning often depended primarily on regulatory classification categories.

Under ECL:

  • poor collateral data directly distorts LGD estimates,
  • which in turn affects provisioning accuracy.

Consequently, banks require stronger collateral data governance covering:

  • ownership details,
  • charge ranking,
  • enforceability status,
  • valuation history,
  • insurance validity,
  • legal disputes,
  • document deficiencies,
  • jurisdiction mapping,
  • cross-collateralization,
  • guarantor linkage,
  • and recovery experience.

Collateral systems must therefore evolve toward:

  • centralized data architecture,
  • standardized metadata frameworks,
  • integrated document repositories,
  • and enterprise-wide risk visibility.

9. Integration of Collateral Systems with ECL Engines

Perhaps the most important architectural implication of the ECL framework is the need for deep integration between collateral systems and enterprise risk engines.

Historically, collateral systems often operated independently from:

  • risk rating systems,
  • provisioning engines,
  • recovery systems,
  • and credit monitoring platforms.

Such silo-based architectures are unlikely to remain sustainable.

Under ECL, collateral systems must integrate with:

  • ECL computation engines,
  • staging models,
  • early warning systems,
  • limit management systems,
  • recovery platforms,
  • legal systems,
  • and enterprise risk management frameworks.

The future architecture requires collateral to function as a live risk parameter across the institution.


10. Role of Collateral in Stage Migration

Collateral deterioration also influences staging assessment under ECL.

Weakening collateral quality may indicate:

  • increased credit risk,
  • deterioration in borrower viability,
  • or declining recovery prospects.

Accordingly, collateral behaviour may influence:

  • Stage 1 to Stage 2 migration,
  • Stage 3 identification,
  • restructuring decisions,
  • and impairment assessments.

This significantly expands the influence of collateral beyond traditional provisioning support.


11. Supervisory Expectations in the New Regime

Although ECL introduces model-driven provisioning, regulators are unlikely to abandon prudential conservatism entirely.

Supervisory overlays may continue for:

  • unsecured exposures,
  • stale valuations,
  • legal deficiencies,
  • fraud accounts,
  • and stressed sectors.

Therefore, banks should not eliminate existing security erosion controls completely.

Instead, such controls should be redesigned as:

  • supervisory override mechanisms,
  • LGD adjustment triggers,
  • valuation reliability indicators,
  • and risk escalation parameters.

This hybrid approach will provide stronger resilience during the transition phase.


12. Future of Collateral Management

The ECL framework transforms collateral management from:

  • a compliance-oriented support function
    to
  • an enterprise risk intelligence discipline.

Future-ready collateral systems must support:

  • dynamic valuation,
  • predictive analytics,
  • stress testing,
  • recovery modelling,
  • market integration,
  • scenario analysis,
  • and real-time monitoring.

The future banking environment will increasingly require:

  • intelligent collateral ecosystems,
  • objective valuation frameworks,
  • integrated risk architecture,
  • and analytics-driven recoverability assessment.

Banks that continue to treat collateral as a static register of securities may face serious challenges in:

  • ECL accuracy,
  • provisioning adequacy,
  • audit validation,
  • and supervisory assessment.

Conversely, institutions investing in modern collateral intelligence platforms will gain significant advantages in:

  • portfolio risk visibility,
  • capital optimization,
  • recovery forecasting,
  • and proactive credit monitoring.

13. Conclusion

The evolution from traditional IRAC norms to the ECL-based framework does not diminish the importance of collateral management.

It magnifies it.

The earlier prudential architecture viewed collateral primarily as protection after default.

The ECL framework views collateral as a continuously evolving determinant of expected loss.

This is the real transformation.

The disappearance of simplistic “security erosion” thresholds should not be interpreted as reduced relevance of collateral.

Rather, it marks the end of superficial collateral management practices.

The future belongs to:

  • objective valuation methodologies,
  • dynamic recoverability assessment,
  • integrated risk analytics,
  • and intelligent collateral governance frameworks.

In the emerging ECL environment, the central question is no longer:
“Does the bank hold security?”

The real question is:
“How accurately can the bank estimate the realisable economic value of collateral under stressed recovery conditions?”

The answer to this question will increasingly determine:

  • provisioning adequacy,
  • portfolio resilience,
  • capital strength,
  • and the overall quality of credit risk governance within banks.

The new ECL era, therefore, demands not weaker collateral management but stronger, smarter, and significantly more scientific collateral management systems.


Integrating Limit Management with Core Banking and Treasury Systems

Integrating Limit Management with Core Banking

Every bank operates on trust — and that trust is only as strong as its ability to know, at any given moment, how much exposure it carries across counterparties, products, and geographies. Yet many financial institutions, credit and exposure limits are managed in isolation: a treasury system here, a core banking platform there, and a patchwork of spreadsheets holding it all together. 

This fragmentation is no longer a nuisance. It is a risk. 

  • 67% of banks report limit data is siloed across 3+ systems 
     
  • 4–8 hr saverage delay in breach detection with end-of-day monitoring 
     
  • 3× higher operational cost when limits are managed manually 
     

Why integration is the executive priority, not the IT priority 
 

It is tempting to frame system integration as a technology project — something delegated and revisited at a quarterly review. But the consequences of fragmented limit management surface directly on the balance sheet, in regulatory examinations, and in the boardroom after a breach. 

When your core banking system processes a transaction without querying live limit data from your treasury system, you are not running two separate platforms. You are flying blind on one of your most critical risk controls. 

“Real-time limit visibility is not a nice-to-have feature. It is the difference between catching an exposure breach in seconds and discovering it in the morning report.” 

The three integration failure points executives must know 

1. Data latency 

Most legacy architectures rely on batch processing — limits are reconciled at end-of-day or even end-of-week. In fast-moving markets, a counterparty’s exposure can breach limits multiple times within a single trading session before anyone is notified. By the time the report lands, the damage is done. 

2. Siloed approval workflows 

When limit changes require sign-off across treasury, credit, and operations, but each team works from a different system with no shared record, approvals slow to a crawl. More dangerously, temporary overrides granted in one system may never be registered in another — creating phantom headroom that doesn’t exist. 

3. Incomplete counterparty view 

A counterparty that appears within limits in the core banking system may have significant exposure sitting in the derivatives book, the trade finance module, or an off-balance-sheet facility. Without a consolidated view, no single number tells the truth about total exposure. 

What genuine integration looks like 

A modern, integrated limit management architecture connects real-time transaction data from core banking, live market positions from treasury, and limit governance workflows into a single, authoritative control layer. Changes to limits propagate instantly. Breaches trigger alerts before — not after — settlement. And every decision leaves an auditable trail across systems. 

The capabilities that matter most at the executive level: 

  • Real-time limit utilisation visible across all business lines simultaneously. 
  • Automated breach alerts routed to the right approver without manual escalation. 
  • A single limit hierarchy that core banking and treasury systems query from one source of truth. 
  • Full audit log of limit changes, exceptions, and approvals — regulator-ready at any point. 
  • API-based connectivity that integrates without replacing existing core systems. 

Enterprise Credit Limit Management System (ECLMS) 

ECLMS is purpose-built for financial institutions that need unified limit management system without ripping out their existing infrastructure. It connects via secure APIs to your core banking platform and treasury systems, delivering a real-time, consolidated limit control layer — with configurable workflows, breach escalation, and regulatory reporting built in from day one. 

Banks using ECLMS have reduced limit breach response time from hours to minutes, eliminated manual reconciliation between systems, and walked into regulatory audits with complete, timestamped audit trails — without any last-minute scramble. 

Learn more about ECLMS ↗ 

Build, buy, or integrate? 

Most institutions do not need to replace their core banking system to solve this problem. What they need is a dedicated limit management layer that acts as the single source of truth — connecting upward to the board dashboard and downward to every system that touches a limit-sensitive transaction. 

The right question is not “can our current systems be patched to do this?” — most can, to a degree. The right question is: “can we afford the next breach, the next regulatory finding, or the next quarter of manual reconciliation while we wait for a patch?” 

Integration is achievable in weeks, not years, when the architecture is designed for it from the start. 

Final Words  

The institutions winning on risk management in 2026 are not those with the most sophisticated models. They are the ones where the right limit data reaches the right person in real time — automatically, reliably, and with full accountability. Integration is what makes that possible. 

If your limit management still depends on overnight batch runs, manual overrides, or spreadsheet reconciliations between systems, this is not a technology debt issue. It is a strategic risk issue — and it belongs to the agenda today. 

0

Using Real-Time Visibility to Optimize Capital and Collateral

Using Real-Time Visibility to Optimize Capital and Collateral
Dashboard showing real-time liquidity monitoring for commercial banks.
Collateral Optimization

In an era of 24/7 instant payments and volatile global markets, “end-of-day” reporting is no longer enough. For financial institutions, real-time liquidity monitoring has shifted from a regulatory “nice-to-have” to a core operational necessity. This guide explores how banks can move from static spreadsheets to dynamic, automated liquidity management to ensure resilience and compliance.

 
3 Reasons Why Banks Need Real-Time Visibility

A liquidity crisis rarely happens overnight; it happens in the minutes between manual updates. Here is how constant monitoring keeps mid-cap institutions stable: 

  • Instant Stress Detection: Market volatility or sudden withdrawal surge can drain reserves in a heartbeat. 24/7 monitoring allows you to see these trends as they happen, rather than reacting to them the next morning. 
     
  • Optimizing Idle Cash: On the flip side, holding too much “buffer” cash to stay safe hurts your margins. By using a sophisticated Enterprise Collateral and Limit Management System (ECLMS), banks can see exactly how much they need at any given second, freeing capital for higher-yielding investments. 
     
  • Regulatory Confidence: Regulators are increasingly looking for “Intraday Liquidity” mastery. Showing that you have a pulse on your flows 24/7 proves your institution is resilient. 

How ECLMS Transforms Liquidity Risk Management

The ECLMS (Enterprise Collateral & Limit Management System) serves as the central nervous system for a bank’s risk department. By integrating siloed data into a single dashboard, it provides:

  • Automated Alerts: Get notified the moment liquidity ratios dip below a certain threshold.
  • Scenario Stress Testing: Run “what-if” scenarios based on real-time market data to see how your liquidity holds up.
  • Unified View: See collateral, credit limits, and cash flow in one place, eliminating the need for manual spreadsheet reconciliation.

Three Pillars of Crisis Prevention 

  1. Unified Limits: Prevent breaches before they occur by tracking credit and settlement limits across all counterparties in real-time. 
     
  1. Collateral Optimization: Ensure your best assets are being used efficiently. An integrated Enterprise Collateral and Limit Management System (ECLMS) identify high-quality liquid assets (HQLA) instantly, ensuring you are always “audit ready.” 
     
  1. Automated Alerts: Instead of a staff member finding a discrepancy in a spreadsheet, the system flags potential liquidity gaps automatically, allowing for immediate intervention. 

The Bottom Line 

For executives, the goal isn’t just to survive a crisis—it’s to build an institution so transparent and efficient that a crisis never gets the chance to start. 24/7 monitoring isn’t a luxury; it’s the standard for modern, responsible banking. 

1

Beyond Allocation: The Strategic Art of the “Cheapest-to-Deliver” Asset

Cheapest-to-Deliver Asset

 In an era of Basel III/IV constraints, fluctuating interest rates, and heightened liquidity coverage ratios (LCR), how a firm manages its inventory can significantly impact the bottom line. 

While “Collateral Allocation” is a functional necessity, “Collateral Optimization” (built on the Cheapest-to-Deliver principle) is a source of competitive alpha. 

The Evolution: From “First Available” to “Best Available” 

In the legacy banking model, collateral management was reactive. Today, with the shift toward T+0 and instant settlement, it must be predictive. 

  • Collateral Allocation (The “What”): A linear, rule-based process. If a Clearing Corporation (CCIL/NCL) issues a margin call, the system identifies any eligible asset and moves it. It solves the settlement but ignores yield leakage. 
     
  • Collateral Optimization (The “How”): A multi-dimensional mathematical challenge. It evaluates the entire inventory against a matrix of haircuts, funding costs, and reinvestment yields to identify the most efficient movement of value. 

The “Cheapest-to-Deliver” (CTD) Engine 

The CTD concept, borrowed from the futures market, is the heartbeat of optimization. It refers to the specific asset that satisfies a requirement while imposing the minimum economic drag on the firm. 

To determine the CTD asset, sophisticated fintech engines calculate the true “Cost of Carry” for every security in the pool: 
 
 
By delivering the CTD asset—perhaps a State Development Loan (SDL) rather than a high-demand Benchmark G-Sec—a firm preserves its most liquid assets for higher-yielding activities like TREPS lending or satisfying regulatory buffers. 

The Strategic Value Proposition 

1. Enhanced Return on Equity (ROE) 

Every basis point saved on funding costs via CTD selection drops directly to the bottom line. By avoiding “over-collateralization” (posting higher quality assets than required), firms unlock capital that can be deployed into higher-yielding credit books. 

2. Liquidity Resilience 

Optimization provides a bird’s-eye view of “collateral velocity.” During periods of market stress, an optimized engine can automatically substitute “expensive” collateral with “cheaper” alternatives, ensuring that the most liquid securities remain available for emergency RBI windows or MSF. 

3. Operational Scalability 

Manual allocation cannot keep pace with 24/7 digital assets. AI-driven optimization automates the CTD selection process across thousands of ISDA/CSA agreements and margin pledge-repledge workflows simultaneously. 

The Intelligence Layer: AI & DLT in Real-Time CTD 

The manual “triage” of collateral is becoming obsolete. The complexity of modern markets requires an intelligence layer that processes millions of data points in milliseconds. 

  • AI-Driven Predictive CTD: Machine Learning models now analyze historical volatility and repo rate fluctuations to predict liquidity squeezes before they happen. It identifies the CTD not just for today, but for the projected lifecycle of the trade. 
  • Tokenization & Atomic Settlement: Using tokenized assets, the transfer of collateral and the updating of the ledger happen simultaneously. This eliminates the “settlement gap” where capital is often trapped and unproductive. 
  • Automated Substitution: If an asset currently posted as collateral becomes “expensive” (e.g., its market value rises or it’s needed for a high-yield trade), DLT-based systems can automatically trigger a substitution with a “cheaper” eligible asset in real-time. 

Comparison for Decision Makers
 

Factor Legacy Allocation Strategic Optimization (CTD) 
Primary Driver Operational Compliance P&L Optimization 
Inventory View Siloed by Desk/Entity Centralized & Holistic 
Asset Selection “First Available” “Cheapest-to-Deliver” 
Impact Cost Center Profit Center / Alpha Generator 

The Bottom Line: Why ECLMS is Non-Negotiable 

To execute a “Cheapest-to-Deliver” strategy at scale, a banking enterprise needs a centralized nervous system. An Enterprise Collateral & Limit Management System (ECLMS) bridges the gap between high-level risk appetite and granular operational execution. 

A robust ECLMS transforms collateral from a static line item into a strategic tool through Unified Inventory Visibility: breaking down silos between repo, derivatives, and treasury desks to create a single “global pool” of assets. 

In 2026, the firms that win are those that treat collateral as a dynamic asset class. Moving to a CTD-based model isn’t just an operational upgrade—it’s a fundamental shift in capital efficiency.