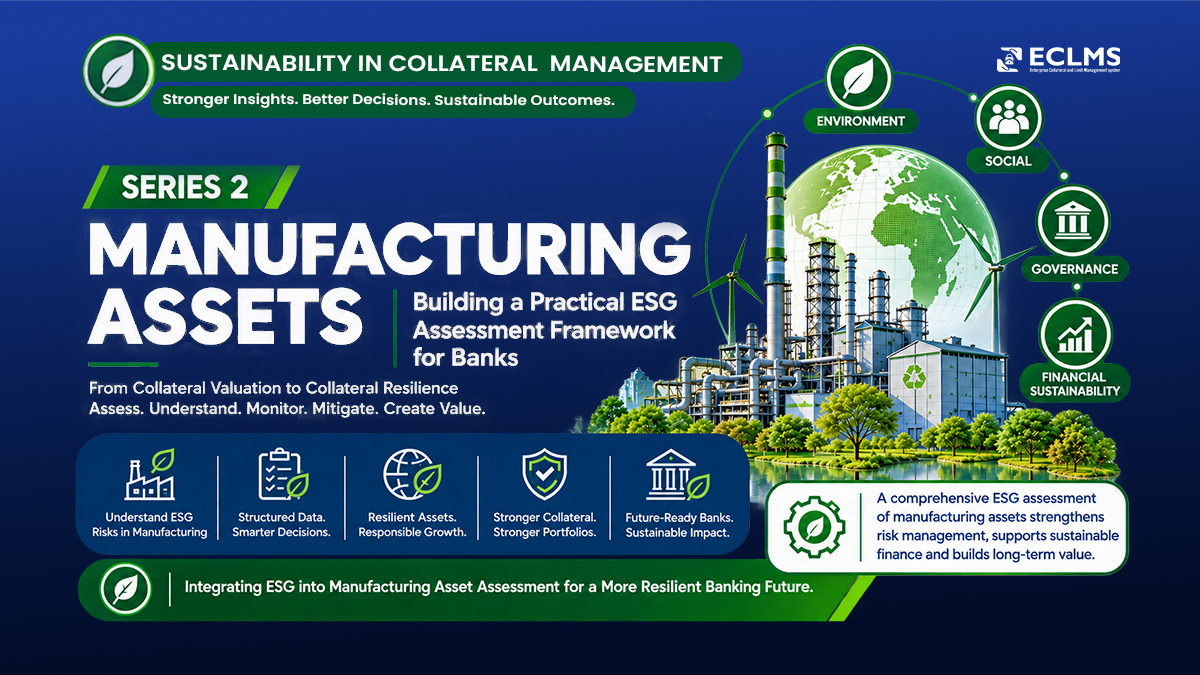
In the first article of this series, we discussed the need to look beyond the conventional legal and financial characteristics of property collateral and progressively build a sustainability profile of the underlying asset.
Banks are indirectly involved in various manufacturing activities through funding; therefore, ascertaining sustainability aspects is critical when orienting their funds towards environment friendly activities. Evaluating sustainability in respect of manufacturing assets presents a significantly more complex challenge.
A manufacturing facility cannot be assessed only by asking whether the building is energy efficient, exposed to flooding, adequately insured or environmentally compliant.
The industrial activity taking place within that property can itself materially influence the sustainability and risk profile of the collateral.
A steel plant, pharmaceutical unit, automobile factory, textile processing facility and food-processing plant may all be classified broadly as manufacturing assets—but their environmental footprint, resource dependencies, regulatory requirements and transition risks can be substantially different.
From a banker’s perspective, this raises an important question:
How do we build a manufacturing sustainability assessment that is comprehensive without creating hundreds of different questionnaires?
A Layered Approach to Manufacturing ESG Assessment
In our view, the solution lies in a layered data architecture.
Instead of attempting to design one universal questionnaire—or a completely separate questionnaire for every industry—the assessment can be progressively constructed through four layers:
1. Common Manufacturing ESG Dataset: A baseline dataset applicable to manufacturing facilities irrespective of the industry.
2. Industry Group-Specific Dataset: Additional parameters based on the broad nature of the manufacturing activity—for example, metals, chemicals, automotive, textiles or food processing.
3. Industry / Activity-Specific Dataset: Specialised parameters relevant to the actual manufacturing process.
4. Site & Location-Specific Risk Dataset: Physical climate and environmental risks associated with the geographical location of the facility.
The resulting assessment can therefore be represented conceptually as:
Manufacturing ESG Assessment = Common Manufacturing Data + Industry-Specific Data + Activity-Specific Data + Site/Climate Risk
What Should the Common Manufacturing Dataset Cover?
Before getting into industry-specific requirements, Indian banks need a consistent baseline. The common manufacturing ESG dataset that we have been working on covers the following major areas:
The accompanying infographic provides an illustrative view of the data points that may be considered within these areas.

Why This Matters to a Banker
For banks, sustainability data should ultimately contribute to better risk understanding rather than becoming another compliance-oriented data collection exercise.
A structured manufacturing sustainability profile can potentially support:
• Identification of environmentally sensitive collateral
• Assessment of physical climate vulnerability
• Identification of energy-, water- and carbon-intensive assets
• Monitoring of environmental clearances and regulatory compliance
• Assessment of transition risk
• Identification of green or transition-finance opportunities
• Monitoring of climate-related insurance protection
• Portfolio concentration analysis across ESG-sensitive industries
• Identification of assets requiring enhanced monitoring
• Future assessment of sustainability implications for collateral value and marketability
Absolute Numbers Alone May Not Tell the Story
Manufacturing assessment also requires greater emphasis on intensity metrics.
A large manufacturing facility will naturally consume more electricity, water and other resources than a smaller facility.
Therefore, recording only absolute consumption may not provide a meaningful basis for comparison.
Where appropriate, the framework should also derive measures such as:
Energy Intensity = Energy Consumption / Production Output
Water Intensity = Water Consumption / Production Output
Carbon Intensity = GHG Emissions / Production Output
This enables comparison across facilities and, more importantly, monitoring of improvement or deterioration in the sustainability performance of the same asset over time.
Data Collection Should Not Mean Manual Data Entry
Another important consideration is the source of sustainability information.
Not every data point should be manually entered.
A mature collateral sustainability framework should progressively distinguish between:
• Customer / User Reported Data
• Document-Sourced Data
• Existing Bank / Collateral Data
• External API / GIS-Sourced Data
• System-Calculated Data
For example, production and energy-consumption information may come from the customer or supporting documents, while flood, cyclone, earthquake, heat stress or water-stress exposure can increasingly be obtained from external geospatial sources.
Carbon intensity, water intensity and composite risk indicators can then be system-calculated.
This approach can substantially improve both the reliability and operational feasibility of ESG data collection.
Entity ESG Risk and Asset Sustainability Risk Are Different
As discussed in Series 1, this distinction becomes even more important for manufacturing.
A manufacturing company may have a corporate ESG rating, but an individual plant offered as collateral can have its own sustainability characteristics.
The plant may be:
• located in a water-stressed region,
• dependent on carbon-intensive energy,
• exposed to flooding,
• operating under environmental clearances approaching expiry,
• generating hazardous waste, or
• operating with significantly better sustainability characteristics than the borrower’s other facilities.
Therefore:
Borrower ESG Profile ≠ Individual Manufacturing Asset Sustainability Profile
Banks may ultimately need visibility into both.
From Collateral Valuation to Collateral Resilience
Traditional collateral management asks:
What is the asset worth today?
A sustainability-enabled collateral framework introduces additional questions:
How environmentally sustainable is the asset?
How exposed is it to physical and transition risks?
Could these risks influence its future operations, insurability, marketability or value?
And perhaps most importantly:
How resilient is the collateral over the remaining life of the bank’s exposure?
This is where we believe sustainability can become an important additional dimension of modern collateral management.
The objective should not be to turn the collateral management system into a full-scale enterprise ESG platform.
Rather, it should ensure that sustainability characteristics capable of materially affecting collateral risk are identified, structured, monitored and made available to the bank’s wider risk-management ecosystem.
#CollateralManagement #ESG #Sustainability #Manufacturing #ClimateRisk #Banking #RiskManagement #GreenFinance #SustainableFinance #ClimateResilience